Thursday, July 22, 2010

Raise Your Home Value

Compliments on your remodeling efforts are always a welcome payoff, but nothing beats seeing your home value rise as a result of your hard work.

It can be tricky to determine which home improvement projects are worth the sweat and which aren't. To gain the most from your improvements, select projects that do more with what you already have.

Projects that add value:

  • Kitchen and bath updates
  • Replacement of exterior siding
  • Fresh interior paint
  • Rejuvenation of landscaping

Less-profitable projects share one of three flaws: they cost too much, they involve a space that isn’t used every day or they reflect too much of your personal taste.

Projects that won't raise your home's value include:

  • Turning a spare bedroom into a home office
  • Conversion of a garage into a family room
  • Screening an outdoor room
  • Adding a deluxe kitchen upgrade into anything but an upscale home

    Take a look at the sweat scale and see how some of the most popular home improvements rate:

    The Sweat Scale

    $ - You’ll break a sweat trying to break even at resale.
    $$ - Probably not worth the sweat you’ll put into it.
    $$$ - Sweat the cost or style details to make money on this project.
    $$$$ - A good bet for turning the sweat of your brow into sweat equity.
    $$$$$ - You’ll be making money before the sweat dries.

    Kitchen Update
    $$$
    Doing a kitchen update instead of a kitchen remodel is like getting Botox® instead of a face-lift – it’s cheaper, it’s faster and it can hold you over for years. Got a kitchen so outdated that Martha Washington would be comfortable cooking there? Go for the full-blown remodel.

    "If you have to overhaul the plumbing and wiring or you have galley kitchen that can be transformed into an open kitchen, go ahead and completely re-do," says Realtor Maggie Sanders, an agent with Coldwell Banker Residential Real Estate, Inc., Naples, Florida.

    For the biggest returns, focus on simple, inexpensive modern touches: recessed lighting, updated pulls, new plumbing fixtures, a solid surface countertop and tile or resilient flooring.

    Bathroom Update
    $$$$$
    If you want to build real sweat equity, forget the bidet and the hand-blown sink when you remodel your existing bathroom (unless you live next door to Paris Hilton). Keep the plumbing where it is and focus on updating outdated fixtures. Strip the bath to the studs and put in a porcelain-on-steel tub with a tile surround, a tile floor, a durable solid-surface vanity, updated lighting, fresh plumbing fixtures and a new toilet.

    "If you have a small bathroom, do a shower only and no tub," says Real Estate Broker Mark Riley of Mark P. Riley Luxury Real Estate Group, Sarasota, Fla. "Slate colored tile will add allure, luster and an expensive look to a bathroom. It looks great with brushed nickel fixtures.

    Replacing siding
    $$$$$
    Give your house a new outfit by replacing the siding and you’ll reap the rewards at resale. According to the National Association of Home Builders’ Cost vs. Value, replacing 1,250 sq. ft. of vinyl siding and trim returns 95.5 percent of cost – and that’s the cost when a contractor does it for you. Upscale siding made from either fiber-cement boards or cellular polyvinyl chloride (PVC) lumber has an even more astounding 103.6 percent return.

    Subtract the cost of the contractor from the profit equation and you could actually make money installing your own siding before you sell your home.

    Interior Paint
    $$$
    Painting can be a great investment in your home or a horrible mistake. It all depends on the color you choose. Pick right and you earn a big payoff. Pick wrong and you devalue your home.

    Don’t think you can escape the issue by painting the walls white. "Too often, homeowners think it’s best to paint the house all the same color, but there is no pizzazz with white walls," says Realtor Lynn Anderson of ZipRealty, East Bay, California. "Soft, muted colors such as pale green or muted beige with white baseboards can still be neutral while greatly improving the look and feel of each room."

    Rejuvenate Landscaping
    $$$
    Your house never gets a second chance to make a first impression. Shabby shrubbery and a patchy lawn make people assume the inside of your house looks as bad as the outside.

    "Keep improvements on par with the other homes in your neighborhood," says Pam O’Connor president of RELO/Leading Real Estate companies of the World. One RELO client in Atlanta transformed his large backyard into a soccer field. "When he sold the house, the owner didn’t recoup his investment because the new owners didn’t care for his choice of landscaping," she says.

    Stick to the basics. Trim or replace overgrown shrubs, plant colorful flowers to highlight your home’s best feature and install a new front door, garage door and mailbox, if necessary.

    Screened Room
    $
    Turning a deck, porch or carport into a sunroom or screened patio creates a great space for entertaining, but it won’t add equity to your home. In fact, you can’t even count that additional square footage as part of the house unless it’s insulated, heated and cooled for year-round use, points out Realtor Nancy Jones, an agent with Hunt Real Estate ERA, Williamsville, NY.

    "A nice sunroom addition on a great house in a highly saleable

Monday, May 3, 2010

Existing-Home Sales Rise 6.8% in March


By Stephanie Armour, USA TODAY


With a tax credit for first-time and repeat home buyers expiring next week, a report Thursday suggests the stimulus hasn't been as effective as a similar credit that dramatically increased home sales late last year.Existing-home sales rose 6.8% to a seasonally adjusted annual rate of 5.35 million units in March from 5.01 million in February, according to the National Association of Realtors. That was also about 16% higher than in March 2009.Last fall, home sales peaked at a 6.5 million annual rate, according to Moody's Economy.com. This spring, they're expected to peak at a 5.7 million annual rate in May.


MORTGAGE RATES: Unchanged from last week."This credit appears to be a shadow of the November credit," says Mark Zandi, chief economist of Moody's Economy.com.The national median existing-home price was $170,700 in March, up 0.4% from March 2009.Distressed homes, typically sold at a 15% discount, accounted for 35% of sales last month - unchanged from February, the National Association of Realtors reported."It doesn't look, at least, that there's been the kind of boom we had last time," says Joel Naroff at Naroff Economic Advisors. "But we have to give it one more month. We have to see April."Total housing inventory at the end of March rose 1.5% to 3.58 million existing homes available for sale, which represents an eight-month supply at the current sales pace, down from an 8.5-month supply in February.The tax credit, which requires a binding contract be signed by April 30 and a deal that closes by June 30, wasn't the only factor behind March's gains. Better weather than in February is believed to have helped, too.In addition, the Federal Housing Administration announced that it is increasing its mortgage insurance premium from 1.75% to 2.25% of mortgages it guarantees. This premium increase, which took effect in early April, was behind a recent five-week surge in mortgage applications, says Brian Bethune at IHS Global Insight."I don't think (the tax credit) has had any impact at all," Bethune says. "You do see it boosting sales a little bit. Maybe it's had a quarter of the effect that the other one did."The current tax credit provides up to $8,000 for first-time home buyers and up to $6,500 for move-up buyers. An earlier tax credit of $8,000 for first-time buyers expired Dec. 1."The biggest benefit is to first-time buyers, and a lot have already taken advantage of it, so we have a smaller potential pool in this go-round," Zandi says.

Home Prices Rise in three California cities


A trio of California cities bucked a nationwide home price decline in February while most of the other metro areas posted losses or flattened out, underscoring the resurgence of the Golden State's coastal markets, data released Tuesday showed.The Standard & Poor's/Case-Shiller index of 20 metropolitan areas was down 0.1% from January on a seasonally adjusted basis, marking the closely watched measure's first decline since home prices began to recover last June.But in a positive sign for housing, the index posted a 0.6% increase from February 2009, its first year-over-year increase in more than three years.The mixed readings come as the expiration of a federal tax credit for buyers looms at the end of this week. Many analysts expect home prices to decline once the incentive runs out — but not nearly as steeply as when values entered a nearly three-year free-fall in the summer of 2006 that helped drag the U.S. into one of the most brutal recessions since the Great Depression.
"Generally, I don't see an upbeat picture, I see the trend as faltering," said David Blitzer, chairman of Standard & Poor's Index Committee. "One of the few spots that seems surprisingly strong is California."California cities saw home prices in February gain 0.8% in San Diego, 0.4% in San Francisco and 0.2% in Los Angeles.Mark Zandi, chief economist with Moody's Economy.com, said the strong showing in California reflected the reduction in foreclosures on the market over the last year. Foreclosures made up 44.3% of the resale market in February, down from an all-time high of 58.8% in February 2009, according to San Diego research firm MDA DataQuick."California is perhaps the most efficient state in respect to resolving its foreclosure issue and so a lot of properties were pushed through the process," Zandi said. "There are now fewer in the pipeline."Although foreclosures may increase in California in coming months, leading to a period of flat prices and perhaps even some declines, the state was "much further along in getting its house in order than most parts of the country," he said.Not reflected in the Case-Shiller numbers are regions in the state farther from the coast where overbuilding was more prevalent and the unemployment rate remains above average, said Richard Green, director of USC's Lusk Center for Real Estate."We are doing a little better than the rest of the country, and that is not particularly surprising because California, in general, didn't overbuild the way Arizona and Las Vegas and Florida did," Green said. "In the places we did, prices collapsed so much it's hard for them to fall much further."In the next two months, some California shoppers have a shot at as much as $18,000 worth of tax credits if they get their timing right.The federal tax-credit program, set to expire Friday, provides up to $8,000 for first-time purchasers and as much as $6,500 for some current homeowners. To qualify for that credit a buyer must sign a contract on a home by April 30 and close the deal by June 30.Adding to that incentive is a statewide credit, which was approved by lawmakers last month and kicks in May 1, for as much as $10,000 for first-time buyers and those purchasing newly built homes.The Case-Shiller index covers three months of data beginning in December, when sales began a three-month slump after what was to have been the federal tax credit's Nov. 30 expiration; Congress in November extended the credit. February's sales data capture that plunge and the traditionally slow winter months. Home sales picked up again in March, and many expect that trend to continue at least through April.Along with the California cities, Las Vegas eked out a 0.1% gain. Fourteen cities posted declines in February over January, with the biggest losses in Portland, down 1.9%; Dallas, falling 1.4%, and Chicago, down 1%. Two cities were flat for the month.

Saturday, April 17, 2010

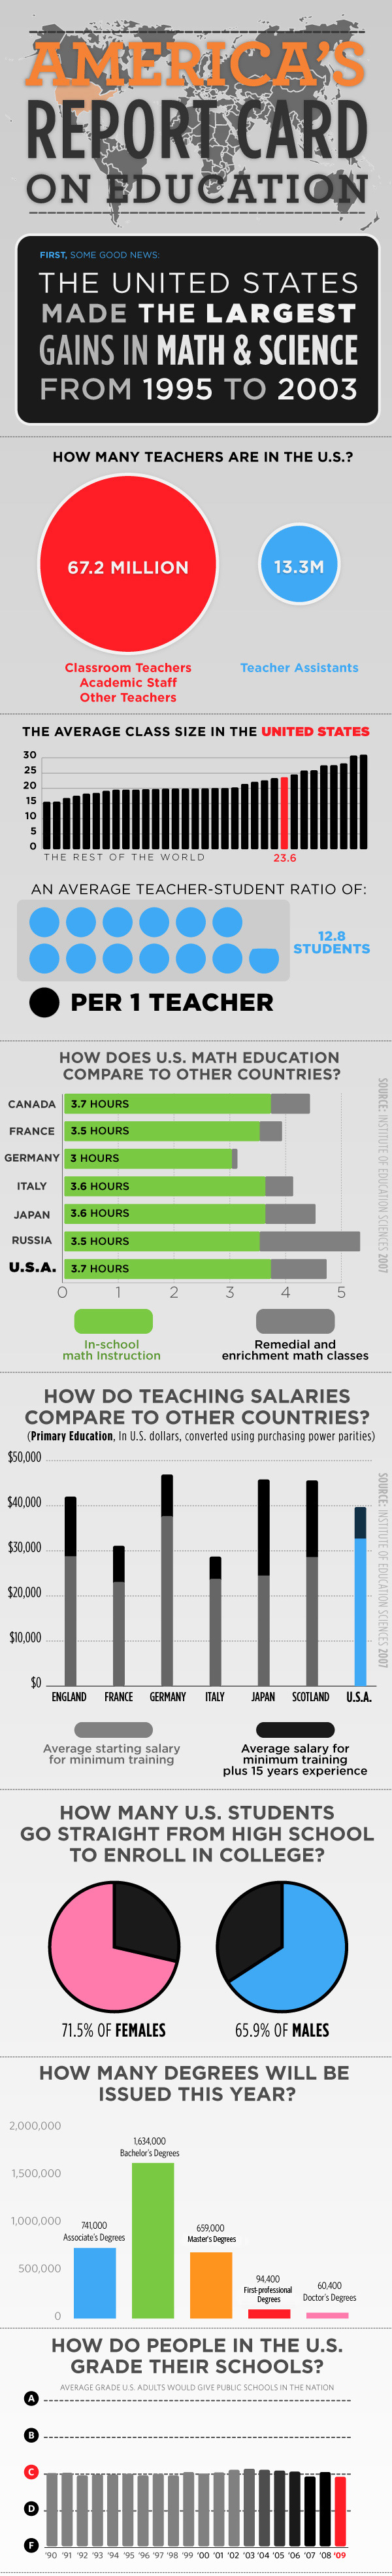
America’s Report Card on Education

America’s Report Card on Education

There’s good news and bad news about the state of public education in the United States. While the greatest gains have been made in Math and Science education from 1995 to 2003, most Americans still only give public schools a below-average grade. Take a graphic look at America’s Report Card on Education to see how public education in the U.S. stacks up against the rest of the world.

America's Report Card on Education

Biggest Celebrity Real Estate Losers

Biggest Celebrity Losers in Real Estate

The Biggest Celebrity Losers
Even celebrity home prices have hit rock bottom.
Suzanne Somers

1. Suzanne Somers

Was: $35 million
Now: $12.9 million

Along with hubbie Alan Hamel, Somers has been working on this huge, 65-acre desert compound outside Palm Springs since 1977. "Les Baux de Palm Springs" mixes the charm of the French countryside with Hollywood touches like Zebra skin rugs (lots of 'em) and massive chandeliers. Even after dropping the price by more than $22 million this property is still on the market, with the current price "available upon request". (Source)

Nicolas Cage

2. Nicolas Cage

Was: $35 million
Now: $17.5 million

Are there any mega-celebrities out there who live in simple, tasteful homes? Certainly not Nicolas Cage, whose old-Hollywood tudor in Bel Air reminds us of the sprawling Xanadu compound from "Citizen Kane". Actually, it's not so much the house as the crap it's filled with. Anyone want a life-sized Mickey Mouse? How about a boulder-sized amethyst geode? The good news is that the property is now being offered at a 50% discount. Anyone got seventeen-and-a-half million bucks lying around? UPDATE: Is this house about to be auctioned off on the courthouse steps? Has Cage defaulted on his mortgage? (Source)

Eddie Murphy

3. Eddie Murphy

Was: $30 million
Now: $14.99 million

Eddie Murphy's seven-bedroom Englewood, NJ mansion known as "Bubble Hill" may be only ten minutes outside of Manhattan, but that doesn't mean he's had an easy time finding a buyer. Bubble Hill has been on the market for at least 5 years. Pro: it's got a bowling alley and a recording studio. Cons: $200k a year in property taxes. UPDATE: Looks like this house keeps dropping! 12.75 million and falling fast. (Source)

Mel Gibson

4. Mel Gibson

Was: $39.5 million
Now: $29.5 million

Another celebrity gets divorced, another mega-Tudor hits the market! This Greenwich, CT mansion was designed by architect Charles Lewis Bowman and built in 1926. It's actually a very tasteful home (we're glaring at you, Nic Cage), if you can get over the fact that Mel Gibson has a reputation for being a huge prick. You know you're a jerk when you drop the price of your house by $10 million but still nobody wants to buy it. UPDATE: Looks like somebody finally bought this place, though the purchase price remains undisclosed. (Source)

Hugh Hefner

5. Hugh Hefner

Was: $27.995 million
Now: $18 million

Why did it take nearly 6 months and a ten million dollar price drop to sell this home? Are there not enough wealthy, single men out there who would pay almost anything for a pimp shack adjacent to the Playboy Mansion? Let me repeat that: you can literally stroll over to the Playboy Mansion in your silk pj's for a round of Texas Hold 'Em with the bunnies. We truly live in strange times. (Source)

50 Cent

6. 50 Cent

Was: $18.5 million
Now: $10.9 million

Mike Tyson. 50 Cent. You. What, you don't think you can fill shoes that big? 50 Cent reportedly spent $10 million on renovations alone fixing up this Farmington, CT mega-mansion that he purchased from Mike Tyson's ex-wife. I guess there aren't many people looking for 52 rooms... one real estate agent went on record saying he'd be surprised if this place sells for more than $5 million. Ouch. (Source)

Richard Gere

7. Richard Gere

Was: $17.995 million
Now: $11 million

It's no secret that Julian Schnabel's Palazzo Chupi units at 360 West 11th Street in Manhattan's West Village have sold poorly. (The units that have sold at all!) Only one big-name sucker took the plunge: Richard Gere. But the star of "Pretty Woman" and "Chicago" never even moved in before the apartment was re-listed at nearly $18 million. More than a year - and several price drops - later, the place finally sold for $11 million. (Source)

Burt Reynolds

8. Burt Reynolds

Was: $15 million
Now: $8.995 million

This old stallion may not regularly trim his famously thick body hair, but he certainly knows how to trim the asking price on his Hobe Sound, FL mansion. The listing has already dropped by about 40%, but without a buyer look for it to continue heading southward. This Mediterranean-style compound borders a wildlife refuge, so watch out for alligators if you take a tour. (Source)

Meg Ryan

9. Meg Ryan

Was: $19.5 million
Now: $14.2 million

Unlike Meg Ryan's reconstructed nose, her 1931 Spanish-style estate is practically flawless. A real movie star house, with ocean views and all that good stuff. Celebrity couples David & Victoria Beckham and Ben Affleck & Jennifer Garner reportedly took tours of the house, but no one was willing to fork over nearly $20 million. For $5 million less, though, it's hard to believe that this house is going to be on the market for very long. (Source)

Alex Rodriguez

10. Alex Rodriguez

Was: $14.9 million
Now: $10 million

A-Rod had to drop the price of his Trump Park Avenue apartment by $4 million before it sold, but even a price drop of nearly $5 million on his Coral Gables home hasn't lit a fire under buyers' checkbooks. Why sell? Looks like Rodriguez is trying to focus on baseball for once, rather than his well-known extracurricular activities. Or maybe the price of a hot dog and a beer at the new Yankee Stadium is just a little too steep? (Source)

Dylan McDermott

11. Dylan McDermott

Was: $11 million
Now: $6.9 million

By all accounts a beautiful residence, McDermott has had major trouble selling this Spanish hacienda-style home in Brentwood, even with a steep price cut. McDermott picked up the house back in 1999 from Melanie Griffith and Antonio Banderas, who bought it in 1997 from Michelle Pfeiffer and David E. Kelly (creator of "The Practice", in which McDermott had a starring role). I'm not saying I've got the cash, but I'd love to live in this house. (Source)

Elle Macpherson

12. Elle Macpherson

Was: $15.5 million
Now: $12.2 million

The falling price on this seven-story Notting Hill, London residence proves that even the UK is being hit hard by the housing crisis. The Victorian property was built in the 1850s and has six bedrooms. It was first listed in the summer of 2008. (Source)

Curt Schilling

13. Curt Schilling

Was: $8 million
Now: $5 million

This house has a history of selling for less than what its sports superstar owners would like to charge. When Drew Bledsoe owned this Medfield, MA home he tried to unload it for $9 million, but eventually had to settle for $4.5 from fellow Boston-area hero Curt Schilling. Schilling had been trying to get rid of it for $8 million, then dropped the price to $5 million. Update: the price has dropped again to $4.5 million. I guess that's really what this house is worth? (Source)

Dan Marino

14. Dan Marino

Was: $15.9 million
Now: $13.5 million

Marino never won a Super Bowl, and he isn't much of a real estate champion either. He's been trying to unload his Weston, FL compound for nearly four years, dropping the price and throwing in freebies like $1.5 million worth of designer furniture and a signed football. A signed football? Wow! That's worth, like... four hundred bucks. (Source)

Scarlett Johansson

15. Scarlett Johansson

Was: $7 million
Now: $5 million

Scarlett Johansson purchased her 1931 Spanish-style home in LA's Outpost Estates neighborhood in 2007 for $7 million bucks. Now it's been listed for just under $5 million... that's $2 million actual dollars that Scarlett is waving goodbye to. Ouch. (Source)

Kimora Lee Simmons

16. Kimora Lee Simmons

Was: $7.8 million
Now: $5.9 million

Kimora may be living "Life in the Fab Lane" as a reality TV star and CEO of Baby Phat, but her real estate woes are the stuff of legend. Along with ex-hubbie Russell Simmons, she's had to drop the price of her Saddle River, NJ home by $7 million. She also cut the price of her own Beverly Hills home by nearly $2 million, but the house has recently been de-listed for lack of an interested buyer. (Source)

Lance Armstrong

17. Lance Armstrong

Was: $12 million
Now: $10.5 million

Armstrong's 447-acre ranch in Dripping Springs, TX includes Deadman's Hole, a beautiful swimming hole that has a giant waterfall. The 7-time Tour de France winner celebrated the birth of his fourth child last year, so maybe he's thinking about keeping the toddler far away from unguarded bodies of water? (Source)

Britney Spears

18. Britney Spears

Was: $7.9 million
Now: $6.5 million

Does anyone really have the energy to listen to one more word about Britney Spears? I didn't think so. Let's just call her a (real estate) loser and be done with it. (Source)

J-Lo & Mark Anthony

19. J-Lo & Mark Anthony

Was: $8.5 million
Now: $7.5 million

Jennifer Lopez and Mark Anthony have sold their understated Bel Air home to a hedge fund manager for $1 million below the asking price. With as much money as they have, do you think they'll even notice? Of course, they were forced to throw in $1.3 million of furniture to close the deal, adding a bit of insult to injury. (Source)

Bruce Jenner & Kris Kardashian

20. Bruce Jenner & Kris Kardashian

Was: $3.4 million
Now: $3.0 million

"Keeping Up with the Kardashians" may be a hit reality TV show, but as we've seen before that hardly insulates you from falling real estate prices. This house was even featured on the first few seasons of the show, but finding a buyer required a 12% price cut. Then again, just like the power couple featured at #19, do you think anyone with the last name Kardashian is going to worry about $400,000? (Source)

Wednesday, April 7, 2010

Short Sales: Obama Offers More Help To 'Underwater' Homeowners

WASHINGTON — The government launched a new effort on Monday to speed up the time-consuming, often-frustrating process of selling your home if you owe more than it's worth.

The Obama administration will give $3,000 for moving expenses to homeowners who complete such a sale – known as a short sale – or agree to turn over the deed of the property to the lender. It's designed for homeowners who are in financial trouble but don't qualify for the administration's $75 billion mortgage modification program.

Owners will still lose their homes, but a short sale or deed in lieu of foreclosure doesn't hurt a borrower's credit score for as much time as a foreclosure. For lenders, a home usually fetches more money in a short sale than a foreclosure. And the bank avoids expensive legal bills, cleanup fees and maintenance costs that follow a foreclosure.

"It's very traumatic and embarrassing and frustrating to go through a foreclosure," said Laurie Maggiano, policy director of the Treasury Department's homeownership preservation office. With a short sale, she said, "your financial issues are your own problem and not neighborhood conversation."

Falling home prices and lost jobs have forced many sellers into this position. For example, in Orange County, Calif., short sales made up about 26 percent of the market in March, compared with 17 percent a year earlier, according to data complied by Altera Real Estate, a local brokerage. In the Minneapolis-St. Paul metro area, about 12 percent of all deals since October were short sales, up from about 8 percent a year earlier, according to the Minneapolis Area Association of Realtors.

The expanded incentives will help accelerate short sales, said Mark Zandi, chief economist at Moody's Analytics. He expects 350,000 homeowners nationwide to use the program through the end of 2012, more than double his earlier forecast.

A short sale appears to be the only way out for Brandee Chambers, 36, of Las Vegas. She got into trouble during the housing boom by taking out a risky loan against her home and using the money to buy two investment properties in Phoenix.

She later lost those two properties to foreclosure, and now she is trying to sell the home she lives in for $209,000, but the mortgage balance is $350,000.

Chambers, who owns two hair salons, says she would rather stay in her home, where she lives with her 14-year old son. But she had no luck getting help with her loan. She said she's resigned to scaling back her lifestyle and renting out an apartment.

Story continues below
"I've had to accept a lot in the last year," she says.

For buyers, though, short sales can be a great opportunity.

Marco Cappelli, 49, a winemaker from Northern California, is planning to buy a short sale this month in the Sierra Nevada foothills. He and his wife are paying $214,000 for a property that had been listed at $270,000. They pair plan to fix it up, install a hot tub and rent it out to vacationers.

Along with the financial incentives, the new government program makes another key change. Mortgage companies will have to set their minimum bid before the house is listed for sale. If the offer is above that, the lender must accept it.

That's a big change from current practice. Lenders generally don't calculate how much money they are willing to accept on a short sale until they have an offer in hand, causing long delays before the sale is approved.

The new program "will give us a degree of efficiency that we have not had in the past," said Matt Vernon, Bank of America's executive in charge of short sales and foreclosed properties.

Under the new process, buyers who submit an offer to purchase a home in a short sale should get a response within two weeks, as opposed to months. If that happens as planned, it would be a big improvement. Real estate agents across the country have complained that lenders are often difficult to reach, sometimes only communicating by e-mail and infrequently at that.

"You're one of 400 properties on a screen," said Dave Bauer, a real estate agent in Danville, Calif.

Some real estate agents who specialize in short sales are optimistic. "It could be the first government program that actually helps Las Vegas," said Steve Hawks, a real estate agent there who specializes in short sales. Most borrowers in Las Vegas, he said, owe so much more on their mortgages than their properties are worth they can't qualify for a loan modification.

The Treasury Department outlined the plan last November, but doubled the original $1,500 in relocation money after realizing that many homeowners need more cash to move out. That's because landlords usually want large deposits from people whose credit records have gone sour after missing mortgage payments.

However, there are plenty of restrictions. To qualify, the home needs to be a borrower's primary residence. Homeowners either have to be behind on their mortgages or on the verge of becoming delinquent.

Currently, the program is not available for mortgages owned or guaranteed by mortgage finance companies Fannie Mae and Freddie Mac, though the two government-controlled companies will soon follow suit, said the Treasury's Maggiano.